One Wallet
Phone Dollars™ toward a new phone for anyone with an NZ mobile.
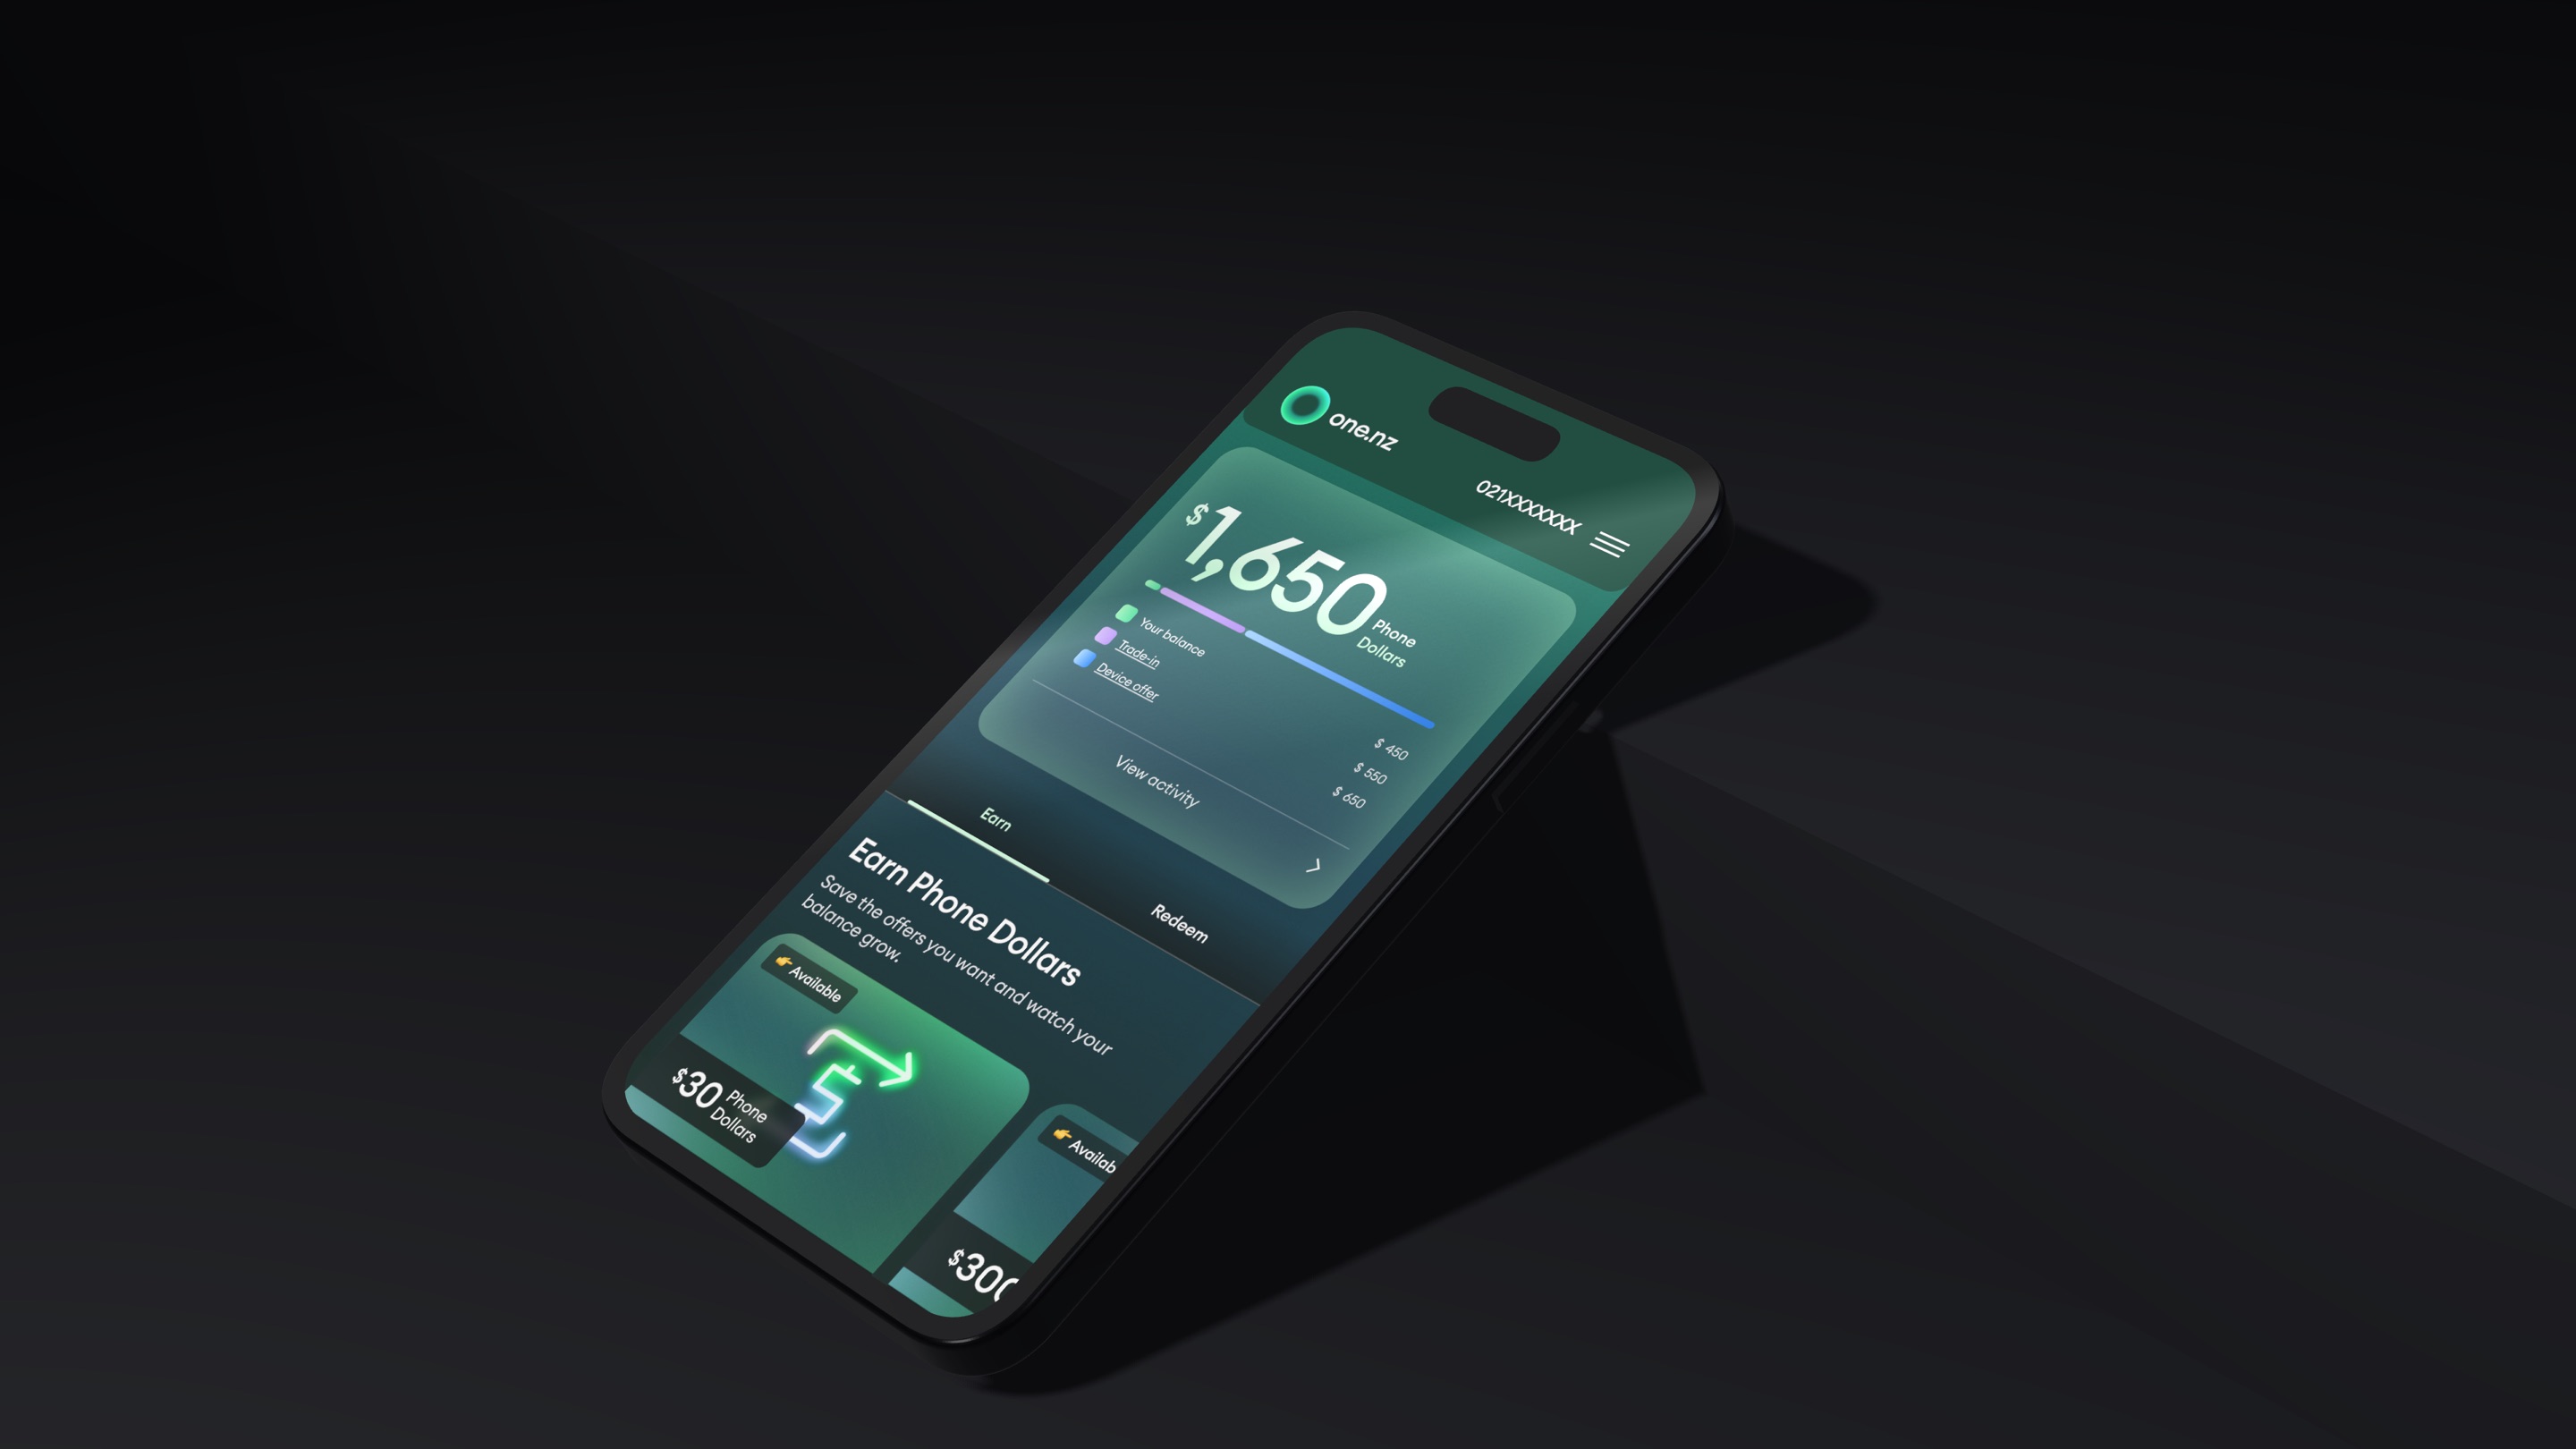
One NZ gives people Phone Dollars, and ways to earn more, to spend on a new phone. Every Phone Dollar is one real dollar off an interest-free phone. In 2025 it opened One Wallet to anyone with a valid NZ mobile, not just customers. My job was to make that value clear and trustworthy.
- Role
- Worked with
- Launched
- Skills
Unfamiliar value invites doubt.
Non-customers had never heard of Phone Dollars. Marketing bet that a large balance would draw them in. Meanwhile, the identity had stalled for months with an agency, putting the product's launch at risk.
- Jul 2025Identity reset
- 9 Sep 2025Launch
- Feb 2026Onboarding fixes
- Apr–May 2026Research
Months stalled. Reset in three weeks.
I listened to what Marketing needed, explored one fitting territory, and gave every decision a rationale that fit the product and the master brand. When McCann recommended the name Phone Dollars, I rolled it out across one.nz and the acquisition web app.
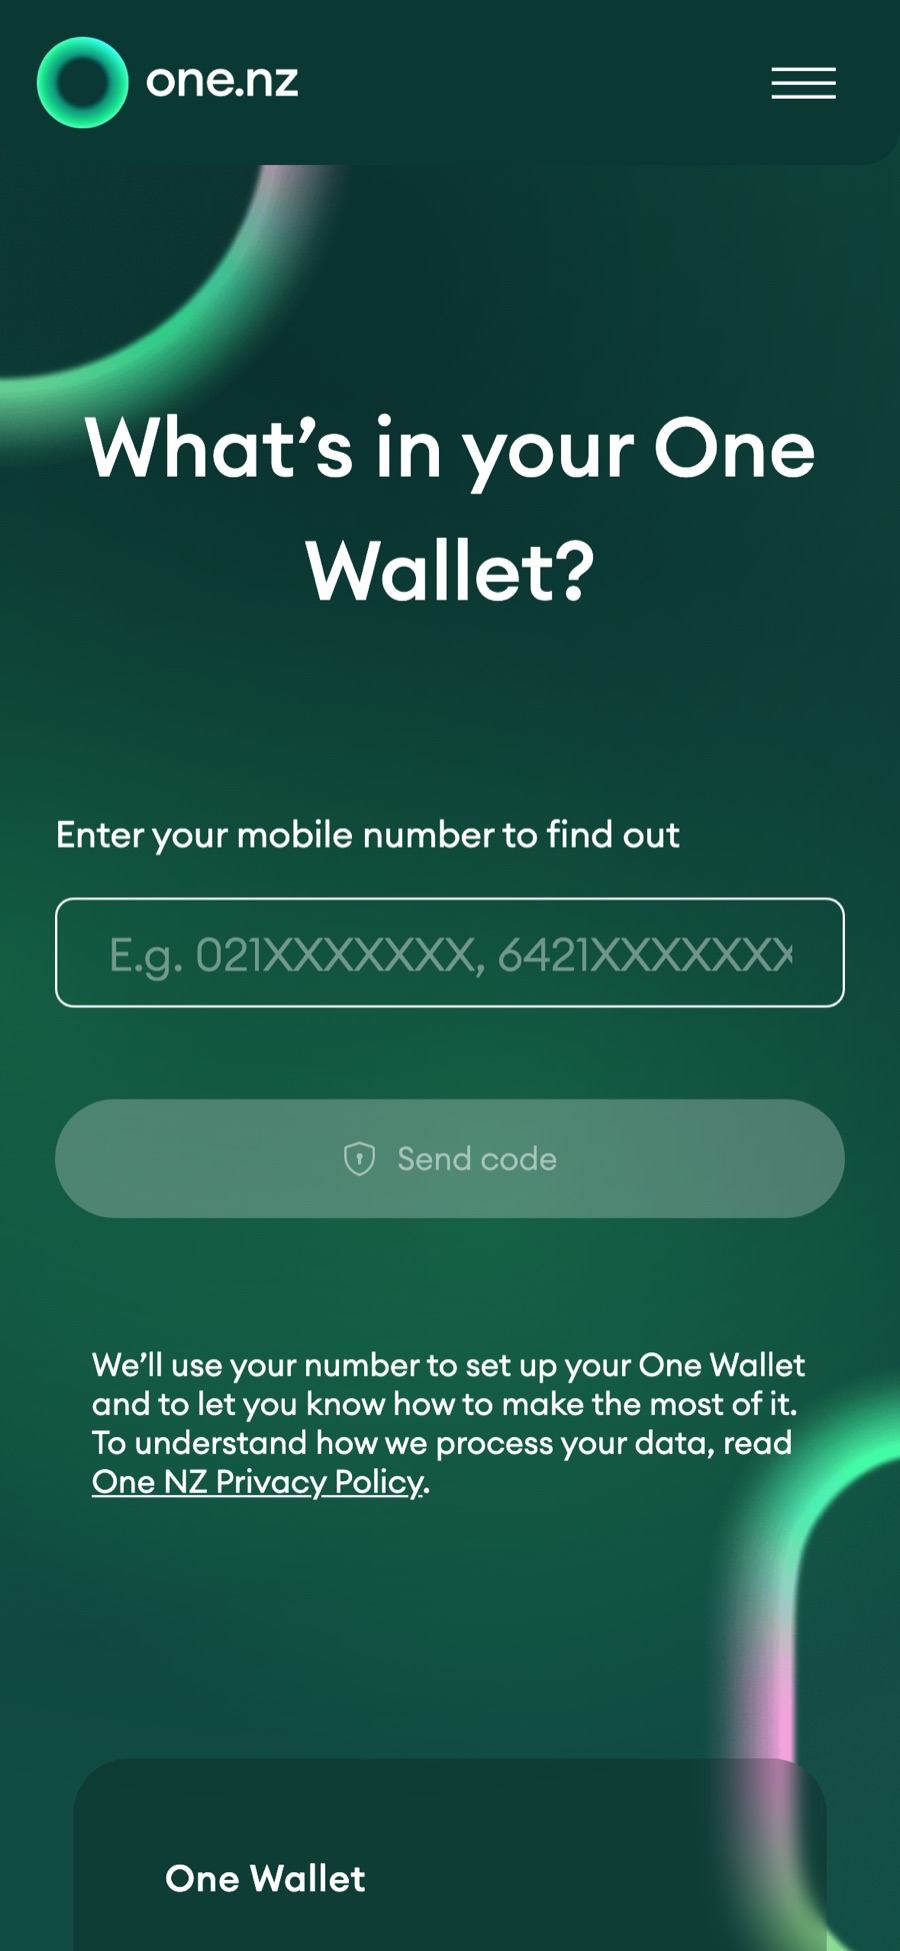
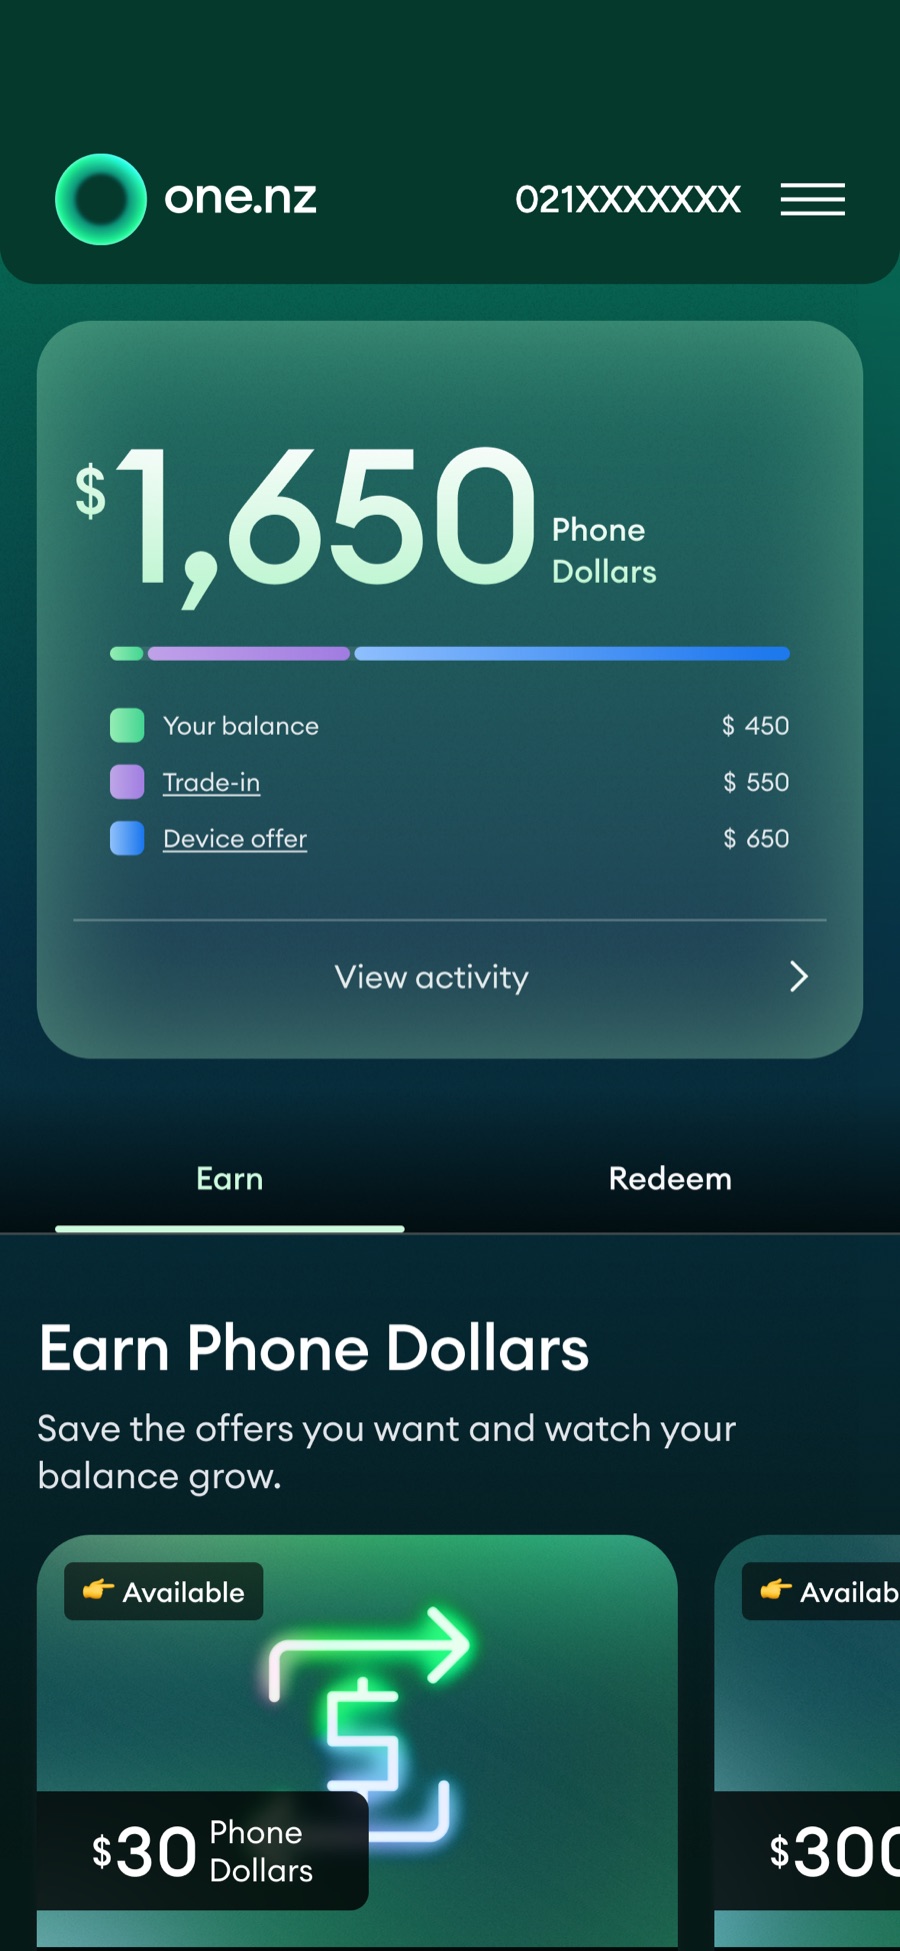
- Identity adoption across the What's in my One Wallet site, app offer cards, one.nz and emails
- ~95%
Make unfamiliar value clear, and believable.
The campaign sent people to What's in my One Wallet to check their balance. I designed it around three rules.
- Lead with who it's forOver 18? You're in.
- Clarity over brevityThe explainer sits right below the number field.
- Put the rules beside the moneyBalance, expiry and conditions together.
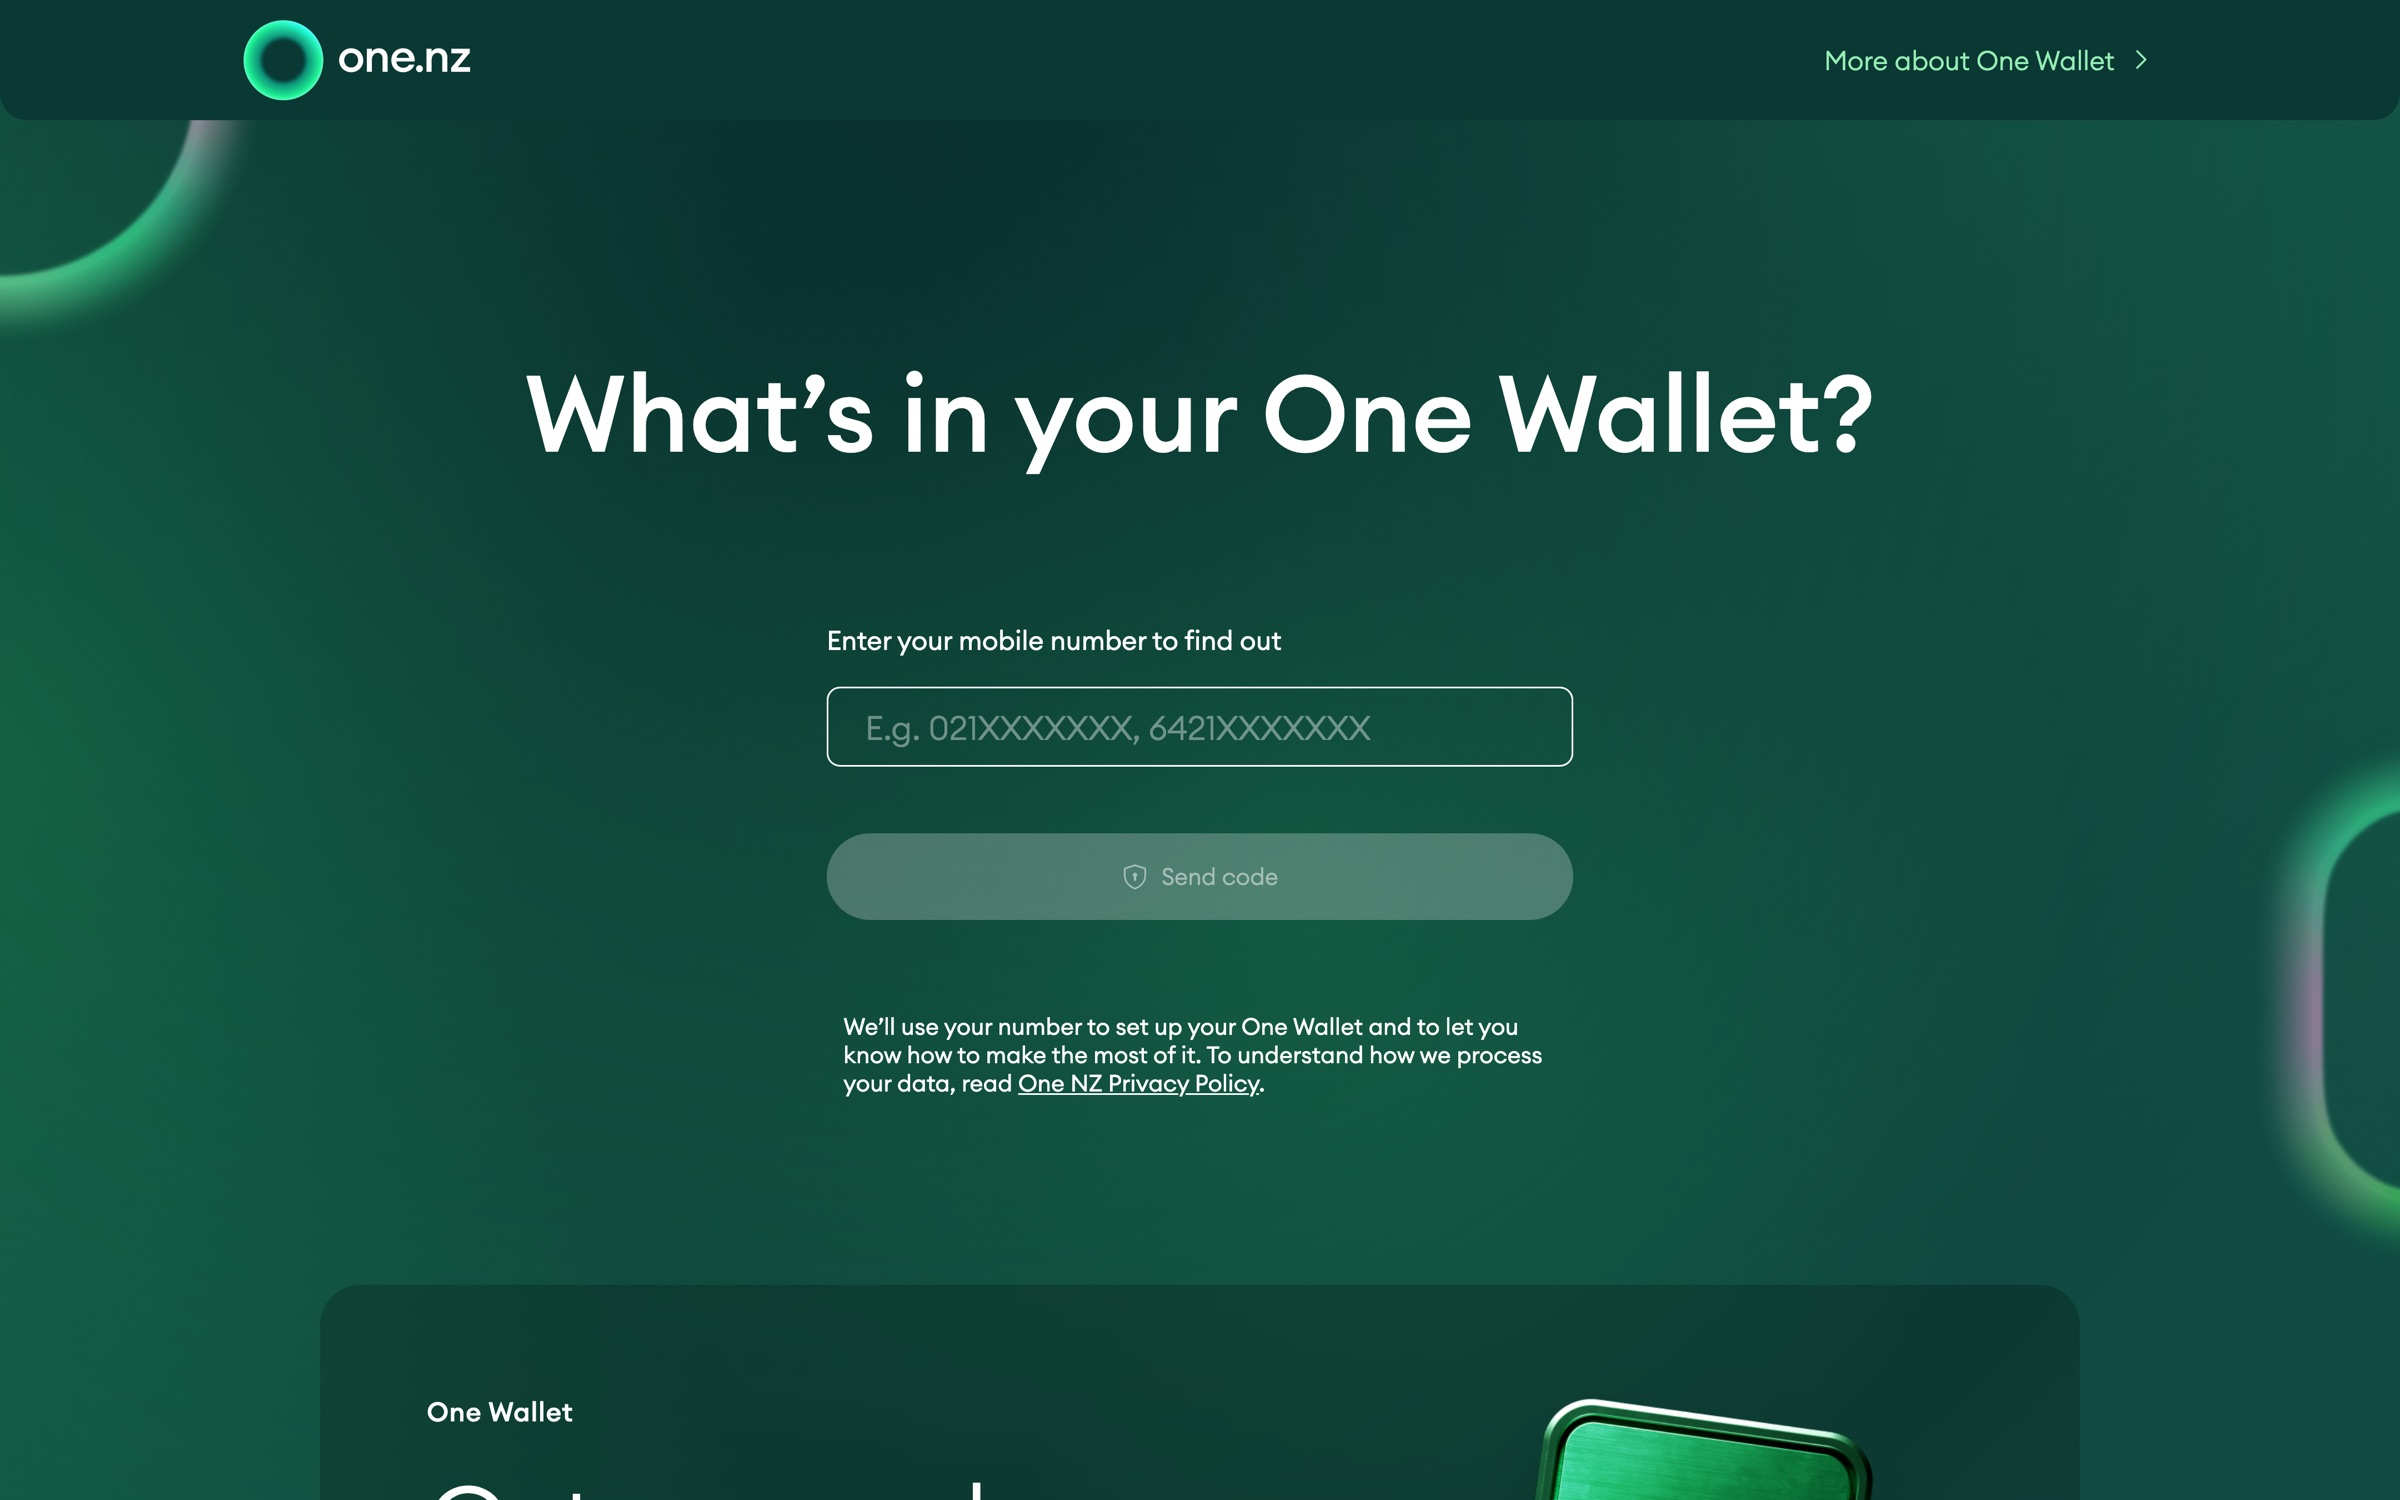
- Non-customer conversion, against a 2.1% target
- 10%
- NPS from engaged users of What's in my One Wallet, from 18 to 35
- +17 pts
Campaign results with many contributors. My part was the digital experience people converted through.
I also restructured the one.nz One Wallet page to lead with customer benefits, with clear calls to action into What's in my One Wallet. Click-through rose from 23% to 53%. Before and after, during the campaign. Not an A/B test.
Improve it while it's live.
After entering their code, people saw a dollar amount and left. The landing page had asked "What's in your One Wallet?", and the number felt like the whole answer. With a design colleague, I added clear next steps.
- Continue to build my balance
- Continue to build my special offer
- Continue to trade-in offer
- Lift in onboarding completion after the fixes
- +5%
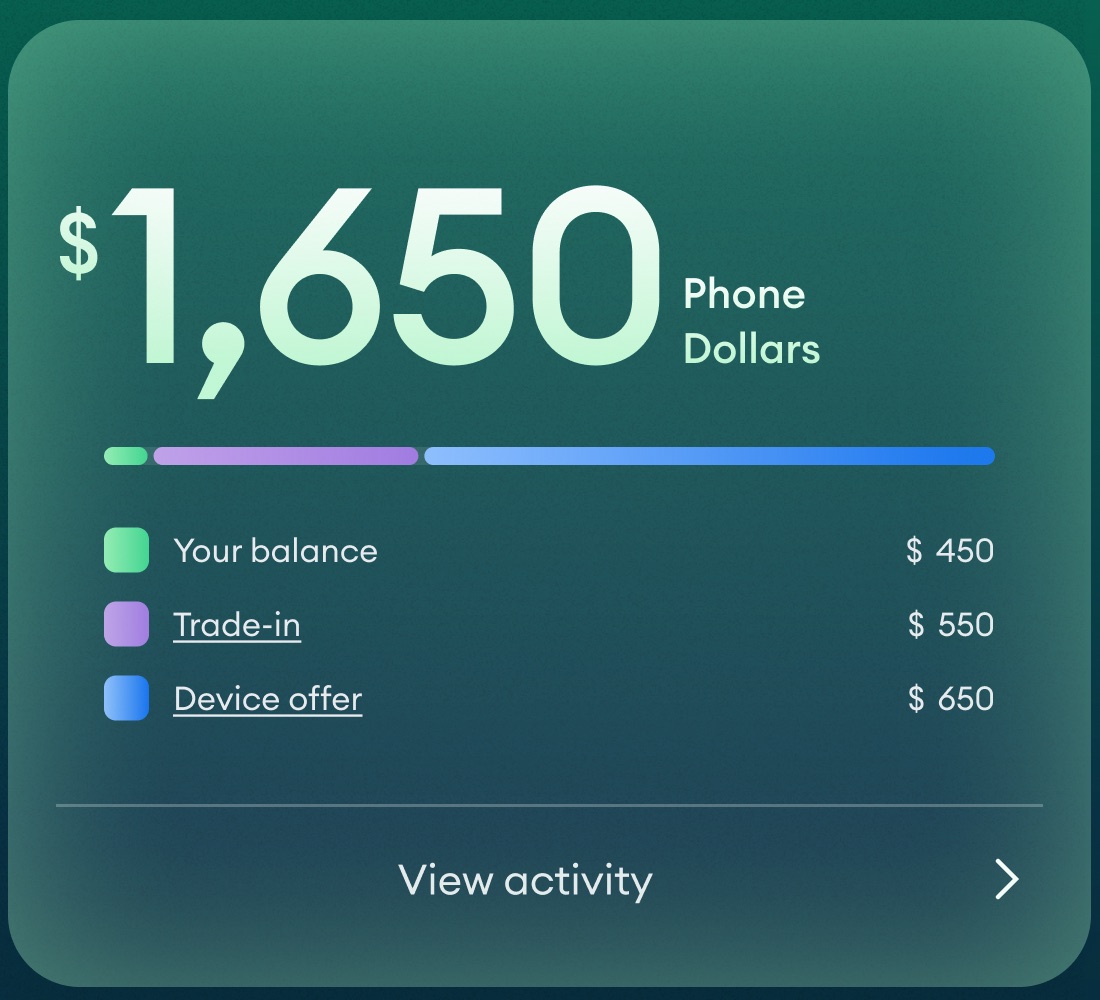
A bigger balance didn't feel like more value.
After launch I ran two studies to understand where people dropped off on What's in my One Wallet. Both qualitative and directional: n=80 and n=69.
- Saving on a new phone was the top appeal in both studies.
- The largest balances raised the most doubt.
- Understanding the concept didn't lift intent on its own.
Next, two tests
- Show what people get before asking for their number, so more start the form.
- Show one trustworthy spendable balance, with conditional amounts secondary, so fewer are disappointed and more redeem.
In money products, clarity is trust.
In the room
- Taking a stalled agency project to a shipped identity
- Why a bigger balance created more doubt
- Where design ended and the agency and McCann began